Vestis Corporation
Second-largest uniform rental company in the U.S. and Canada, with covenant leverage down from 4.72x to 4.10x under new management. I'd buy the equity, where the Street has FY27 at the Q3 run-rate, and hold the Term Loan B-1, which already trades with B1 names.
- Sector
- Uniform Rental
- View
- Market Weight
- Ratings
- B2 / B
- Updated
- 13-Nov-26
Documents
Current View
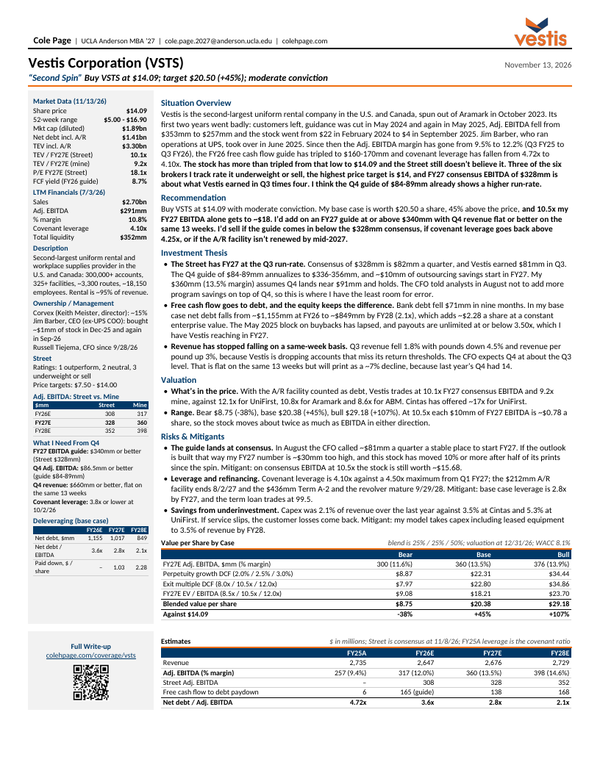
Vestis rents and launders uniforms and supplies mats, towels, restroom and first-aid products to more than 300,000 accounts from 325+ facilities and ~3,300 routes. Rental is ~95% of revenue, and Cintas leads the industry, Vestis is second and UniFirst third. Aramark spun it off in October 2023 with $1.5bn of term loans and kept most of the proceeds. Its first two years went badly: customers left, guidance was cut in May 2024 and again in May 2025, Adj. EBITDA fell from $353mm to $257mm, and the bank lenders loosened the covenant.
Jim Barber, who ran operations at UPS, took over in June 2025. Since then the Adj. EBITDA margin has gone from 9.5% to 12.2% (Q3 FY25 to Q3 FY26), the FY26 free cash flow guide has tripled to $160-170mm and covenant leverage has fallen from 4.72x to 4.10x. Q4 results and the FY27 outlook should come around December 1.
Equity: BUY at $14.09, $20.50 target. FY27 consensus EBITDA of $328mm is about what Vestis earned in Q3 times four, and I think the Q4 guide of $84-89mm already shows a higher run-rate. Free cash flow goes to debt, and the equity keeps the difference. I'd sell if the FY27 guide comes in below consensus. The equity memo has the valuation and the Q4 scorecard.
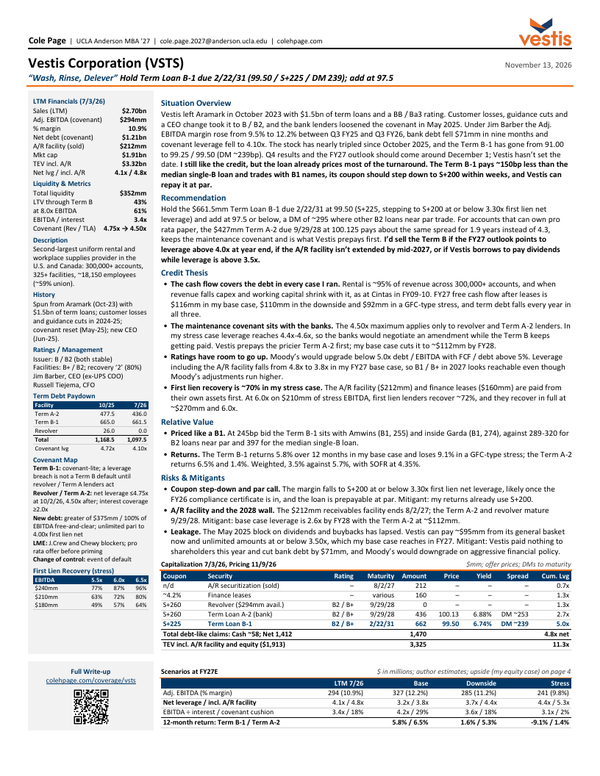
Credit: hold the Term Loan B-1 at 99.50 (S+225) and add at 97.5. The cash flow covers the debt in every case I ran, and the maintenance covenant sits with the banks. But the loan pays ~150bp less than the median single-B loan, its coupon should step down to S+200 within weeks, and Vestis can repay it at par. The credit memo has the covenants, relative value and recovery.
Research
Vestis: BUY at $14.09 Before the FY27 Outlook
Equity Memo· PDFBUY at $14.09 with a $20.50 target. The Street has FY27 EBITDA at the Q3 run-rate and gives no credit for a Q4 the company has already guided to, and the free cash flow is going to debt.
EquityVestis: Hold the Term Loan B-1, Add at 97.5
Credit Memo· PDFHold the Term Loan B-1 at 99.50 (S+225, DM 239) and add at 97.5. The cash flow covers the debt in every case I ran, but the loan already trades with B1 names, its coupon is about to step down and Vestis can repay it at par.
Leveraged Loans