Cole Page
Credit Analyst · cole.page.2027@anderson.ucla.edu · colehpage.com
AppLovin 3Q26: Downgrade to HOLD After the Beat
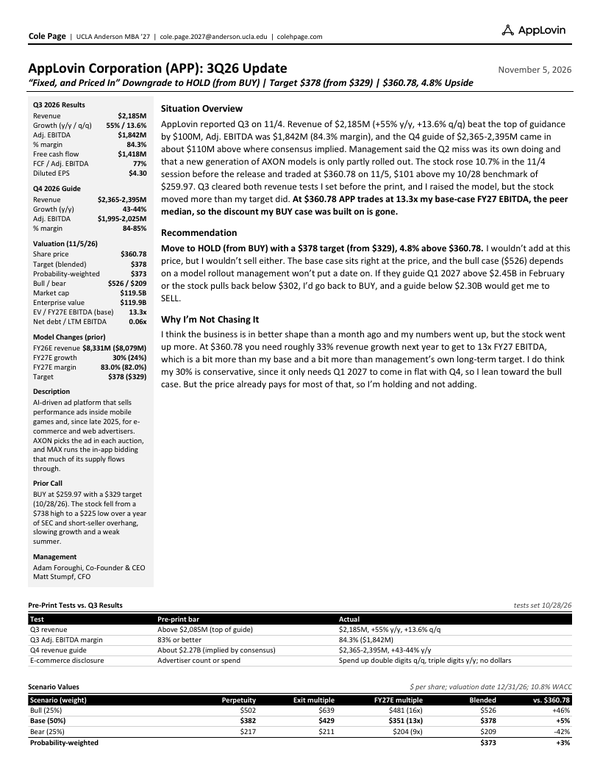
Q3 cleared every test I set on 10/28 and I raised the target to $378, but the stock got to $360.78, 13.3x my FY27 EBITDA and the peer median. The bull and bear cases are now about the same size.
The Short Version
AppLovin reported Q3 on 11/4. Revenue was $2,185M, up 55% y/y and 13.6% q/q and $100M above the top of guidance. Adjusted EBITDA was $1,842M at an 84.3% margin, and the Q4 guide of $2,365-2,395M came in about $110M above what consensus implied. The stock rose 10.7% on 11/4 ahead of the release and traded at $360.78 on 11/5, $101 above the price where I rated it BUY on 10/28.
I raised the target from $329 to $378 and downgraded to HOLD. The business is in better shape than it was a week ago and my numbers went up, but the stock moved more than my target did. At $360.78 it trades at 13.3x my base-case FY27 EBITDA, the peer median, so the discount the BUY case was built on is gone. I wouldn't buy it here, and I wouldn't sell it either.
| 10/28 | 11/5 | |
|---|---|---|
| Rating | BUY | HOLD |
| Price | $259.97 | $360.78 |
| Target (blended) | $329 | $378 |
| Upside to target | +26.7% | +4.8% |
| Bull / bear | $460 / $185 | $526 / $209 |
| Bull / bear vs. price | +77% / -29% | +46% / -42% |
Scoring the Tests
Before the print I wrote down what I'd need to see.
| Test (set 10/28) | Bar | Actual |
|---|---|---|
| Q3 revenue | Above $2,085M (top of guide) | $2,185M, +55% y/y, +13.6% q/q |
| Q3 Adj. EBITDA margin | 83% or better | 84.3% ($1,842M) |
| Q4 revenue guide | About $2.27B (implied by consensus) | $2,365-2,395M, +43-44% y/y |
| E-commerce disclosure | Advertiser count or spend | Spend up double digits q/q and triple digits y/y; no dollars |
Three passed outright. The fourth is partial, since management gave growth ranges for consumer spend but still no dollar figure. One more line from the 10/28 table also fired: I'd listed a share price above $330 as a reason to downgrade.
The Quarter
Nearly all of the growth was price: the 10-Q shows net revenue per installation up 55% and installs up 2%. Most of the extra revenue reached EBITDA, too, with 87% of the year-over-year revenue increase showing up in Adjusted EBITDA. AppLovin doesn't split gaming from consumer, so I'm taking management's word on the mix: gaming grew nearly 50%, and consumer is still the smaller piece, growing triple digits off a base they won't size.
The Q2s are worth a look. Q2 has been AppLovin's softest sequential quarter in each of the last three years (4.8%, 8.6% and 4.4%), so part of what got called a broken model in August was the calendar. Management owned the miss anyway, and I don't want to explain all of it away, but 4.4% looks less alarming next to 2024's 4.8%.
The Q4 guide implies 8-10% sequential growth, against 19.7% and 18.0% in the last two Q4s, in the quarter that should get the most from e-commerce holiday spend. When Jefferies asked about it, the CFO said they guide to what they know. I think the guide is light, and another beat like Q3's would make the bull case much easier to believe.
Costs grew much faster than revenue. R&D was up 132% to $102M and SBC up 149% to $84M, which management tied to training compute and new model development. The margin still rose to 84.3% because data center costs fell as a share of revenue, taking cost of revenue to 11% of sales from 12%. Free cash flow was $1.4B, 77% of EBITDA, after cash tax timing pulled Q2 down to 53%.
The Call
Adam Foroughi said the Q2 miss was the company's own doing, since rivals grew in the same quarter, and that a new generation of AXON models is partly rolled out. He says the new architecture has more room to optimize than AXON 2.0 and works best where data is thin, which is where consumer advertisers sit, but he wouldn't give a timeline. That may be right, and it's also what any CEO would say one quarter after a miss. I can't check it from the outside, though the per-install numbers moved the way they would if he's right. I left the rollout out of the base case and put it in the bull case, where it does most of the work.
Two things on the call cut the other way:
- A weaker Q1. Foroughi said a bigger e-commerce Q4 will be followed by a softer Q1, as the advertisers who spend heavily over the holidays pull back in January. That's real, but AppLovin's Q1s have grown 11-18% sequentially in each of the last three years on gaming's post-holiday push, and my base case only needs Q1 2027 flat with Q4.
- The UBS channel check. A UBS analyst said some gaming advertisers are moving budget to rivals because they expect e-commerce bidders to push up auction prices. Foroughi answered that return on ad spend is higher than it was three years ago and that the advertisers who talk to analysts probably aren't the ones succeeding. If the check is right, it will show up as slower gaming growth, so that's the number I'm watching.
Net leverage is under 0.1x, and the CFO put the long-term level at about 1x, roughly $6.6B of debt capacity on top of a new $3.6B buyback authorization. He called the Q3 buyback step-up opportunistic, and the timing hasn't looked good so far: August and September repurchases averaged about $317 and $311 a share, and the stock closed at $245.51 on 11/3. Foroughi also floated buying data or customer relationships to speed up e-commerce, with MoPub as the model. I'd want to see the price first, given how much of the multiple already assumes consumer works.
The 10-Q added a class action filed 9/16, alleging the company misled investors about how fast its models were improving and about the timeline for an ad-generation tool, plus a derivative suit filed 10/7. No loss contingency is booked. I'm watching it because the complaint is about the same kind of rollout story management is telling now.
What I Changed
FY26 is now actuals plus the Q4 guide midpoint, and I raised FY27 base growth from 24% to 30%, management's long-term target. I left the multiples, the WACC method and the scenario weights alone, so the whole move in the target comes from the cash flows and the 9/30 balance sheet.
| Base case unless noted | 10/28 | 11/5 |
|---|---|---|
| FY26E revenue | $8,079M (+47%) | $8,331M (+52%) |
| FY26E Adj. EBITDA margin | 83.2% | 84.3% |
| FY27E growth (base / bull / bear) | 24% / 33% / 10% | 30% / 40% / 15% |
| FY27E Adj. EBITDA margin | 82.0% | 83.0% |
| FY31E Adj. EBITDA margin | 80.0% | 81.0% |
| SBC (% of sales) | 4.5% | 4.0% |
| Diluted shares | 337.0M | 332.5M |
The bear case is now the Q4 guide annualized, which means no sequential growth for all of 2027. I held the FY27 margin a point below Q3's 84.3% because management will keep buying training compute. My base FY27 revenue of $10,830M is about 7% above where Street estimates were before the print. I expect estimates to move toward it, and the price already roughly assumes they will.
Why HOLD
At $360.78, a 13x multiple on FY27 EBITDA needs about $9.2B of EBITDA to get back to the price. At an 83% margin that's roughly 33% revenue growth next year, a bit more than my 30% base case and a bit more than management's own long-term target. That's a fair price for a business that keeps beating its guide, which is why this is a HOLD and not a SELL.
| Scenario (weight) | FY27E growth | Blended | vs. $360.78 |
|---|---|---|---|
| Bull (25%) | 40% | $526 | +46% |
| Base (50%) | 30% | $378 | +5% |
| Bear (25%) | 15% | $209 | -42% |
| Probability-weighted | $373 | +3% |
The bigger change is the risk/reward. Before the print the bull case was worth 77% upside and the bear case 29% downside. Now they're about the same size, and the base case barely clears the price. On the higher beta a lot of coverage lists use (a 13.9% WACC), the blended value is $338, below the price; on 10/28 the same view still had the stock cheap, at $297 against $260. The bear case is also only a growth stall at the Q4 run rate. A rule change from Apple or Google aimed at how AXON uses data would be worse than that, and none of my scenarios price it.
I've partly changed my mind on the multiple. In October I put the discount down to platform risk and reliance on gaming, and neither went away this quarter. But Q3 showed the Q2 slowdown was fixable, consumer spend is growing triple digits, and the growth gap with peers widened: 30% at an 83% margin against about 22% and 41% for the peer median. On growth-adjusted comps, peers trade at about 0.5x EV/EBITDA per point of growth, which would put APP near 15x FY27. Reddit is the caution, growing about as fast (33%) and trading at 13.5x.
I kept 13x in the target anyway, because raising the multiple on the day the stock jumps 33% is how a target ends up chasing the price. At 15x the blended value would be about $405, 12% above the price, and the exit-multiple DCF alone gives $429. On the bull case's $10.0B of FY27 EBITDA, 15x is worth about $450, and I can see a path to $450-500 if the model rollout keeps landing.
What Would Change My Mind
The big one is the Q1 2027 guide in February. My base case needs about $2,395M, 30% above Q1 2026's $1,842M, and anything well above that would tell me the Q4 guide was light.
| Signal | Now | Back to BUY | Down to SELL |
|---|---|---|---|
| Q1 2027 revenue guide | Base needs ~$2,395M (+30%) | Above $2.45B (+33%), margin 83%+ | Below $2.30B (+25%) |
| Adj. EBITDA margin | 84.3% in Q3; 84-85% guide | Guide below 80% | |
| Gaming growth | Nearly 50% y/y | Slows as e-commerce bidders arrive (the UBS check) | |
| Consumer disclosure | Growth ranges only | First dollar figure for consumer revenue | |
| Legal and platform | 9/16 class action; 10/7 derivative suit | Platform or court finding against AXON's data practices | |
| Share price | $360.78 | Below $302 (20% under target) | Above $454 (20% over target) |